Owner Financing Homes, Land & Commercial for Sale
Buy directly from the owner and pay them over time instead of qualifying for a new bank loan — the seller sets the down payment, the monthly, and the term.
Latest owner financed homes, land, and commercial properties
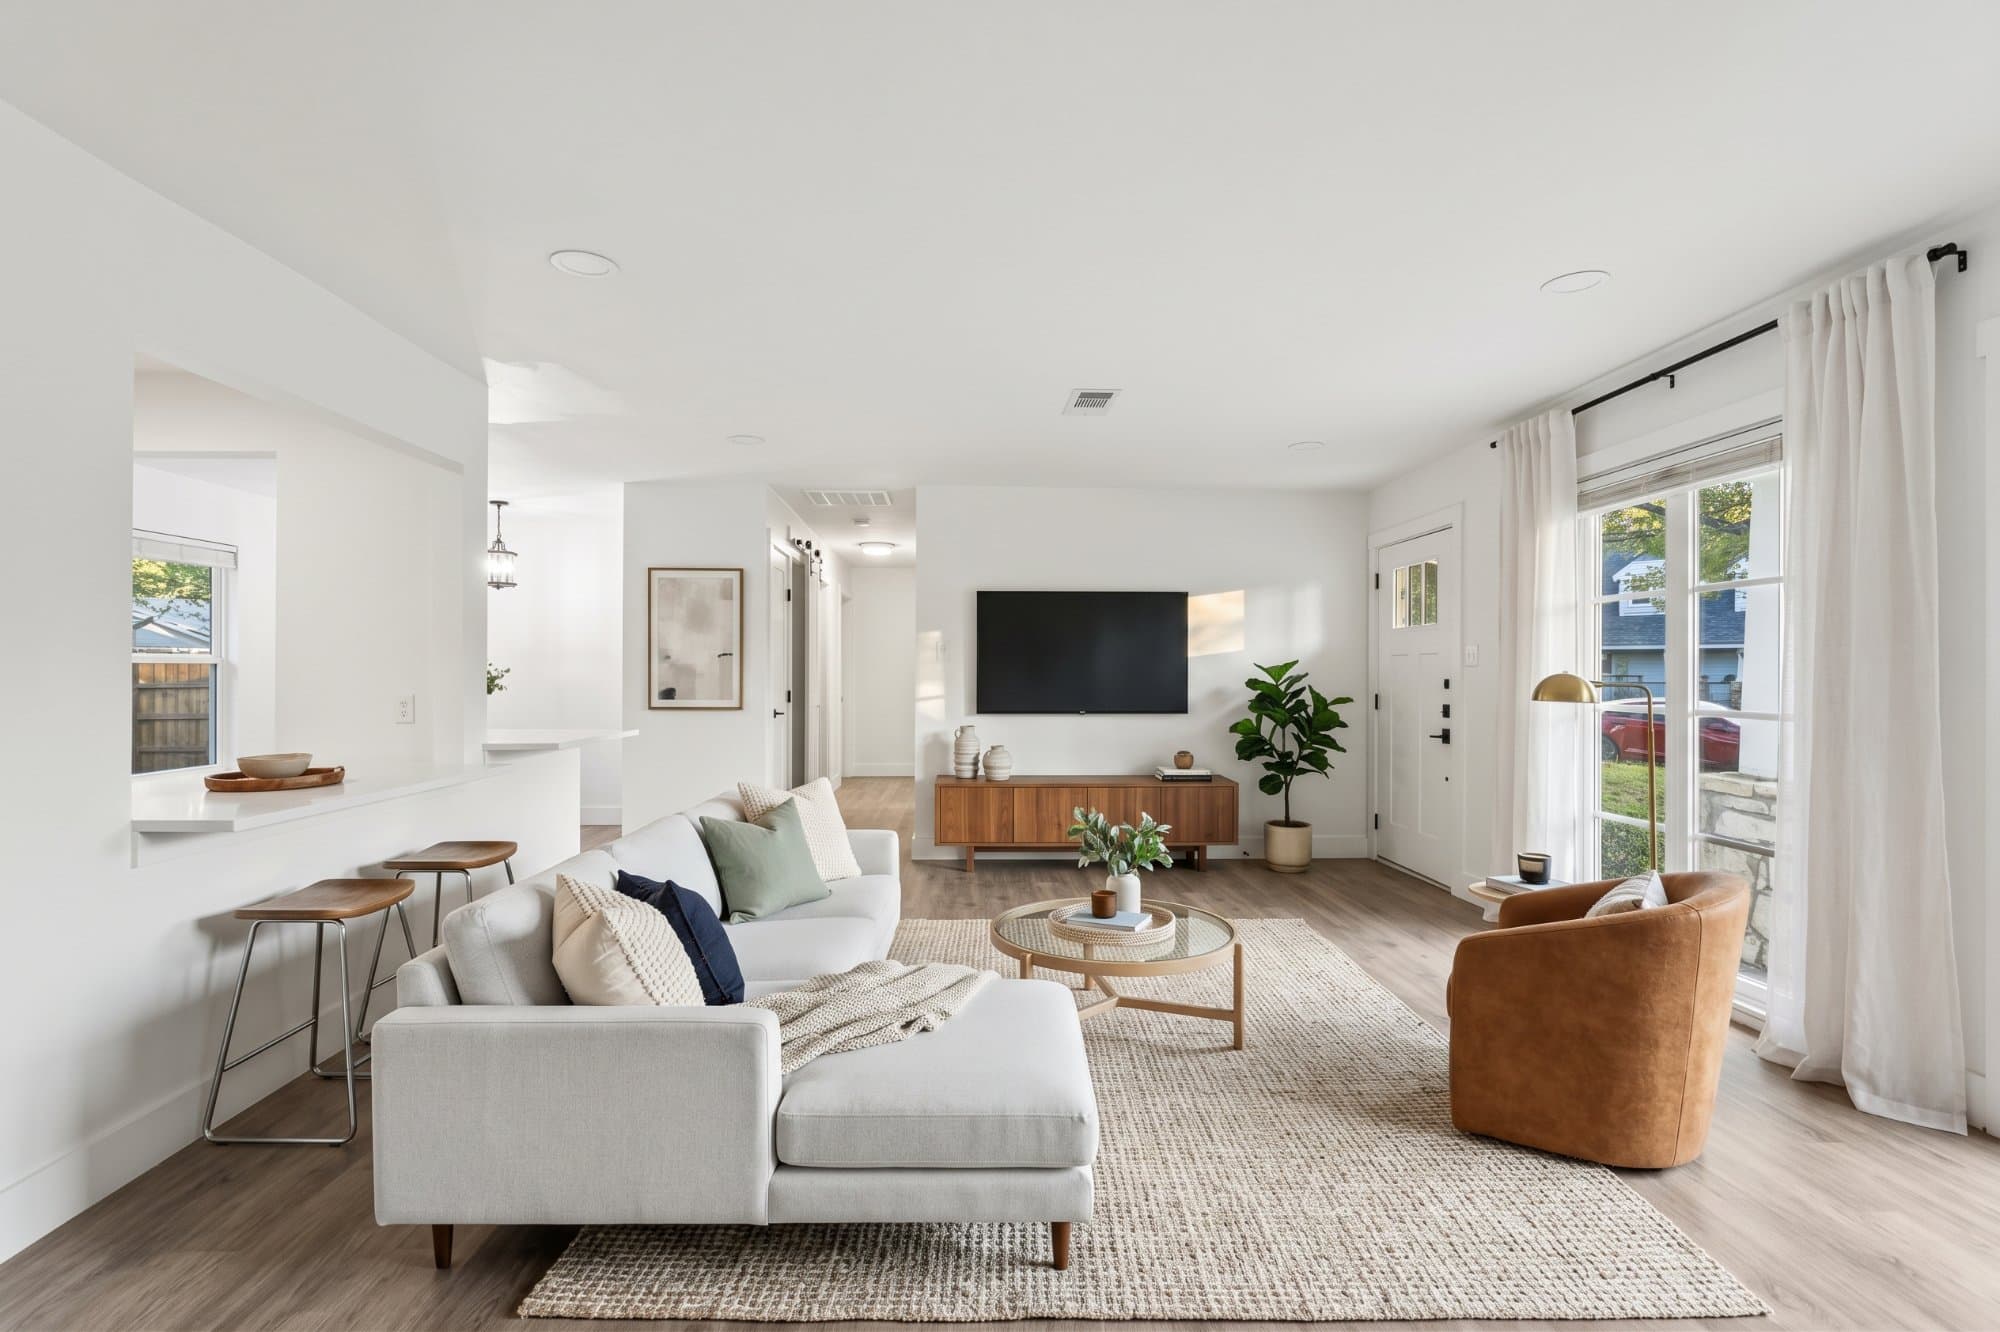 ~$2,706/mo$649,000
Owner Financing · $162.3k down · 3 bd · 1 ba · 1,080 sqft
3 Bed, 1 Bath Home in Austin, TX — Wraparound Mortgage
122 Havana Street, Austin, TX
Down$162.3kRate4.5%Term25 yr ~$260/mo$15,540
Owner Financing · $200 down
Your Florida Land Opportunity
Dunnellon, FL
Down$200RateOn inquiryTerm59 yr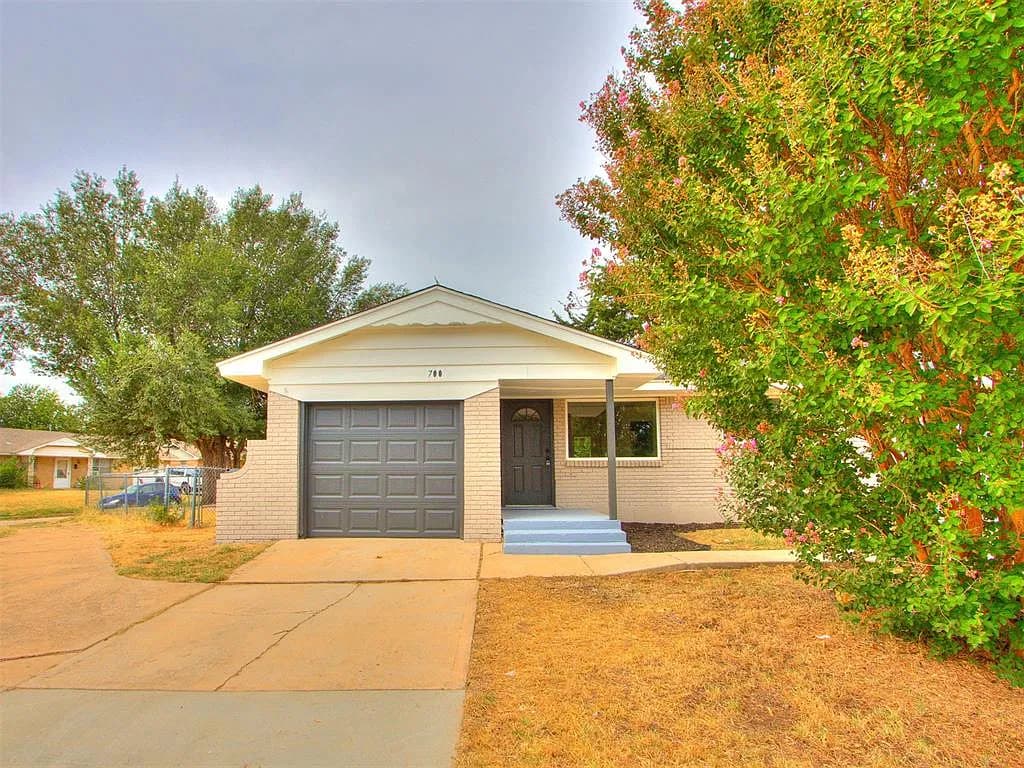 ~$2,200/mo$220,000
Owner Financing · $10k down · 3 bd · 2.5 ba
Home in Moore, OK
700 Butler Street, Moore, OK
Down$10kRateOn inquiry ~$1,730/mo$175,000
Owner Financing · $10k down · 3 bd · 1 ba
Home in Oklahoma City
3025 Southwest 71st Street, Oklahoma City, OK
Down$10kRateOn inquiry ~$3,750/mo$410,000
Owner Financing · $25k down · 3 bd · 3 ba
Home in Oklahoma City
617 Northwest 22nd Street, Oklahoma City, OK
Down$25kRateOn inquiry ~$1,700/mo$170,000
Owner Financing · $10k down · 3 bd · 1 ba
Home in Oklahoma City
3217 Southwest 40th Street, Oklahoma City, OK
Down$10kRateOn inquiry ~$3,000/mo$330,000
Owner Financing · $30k down · 4 bd · 3 ba
Home in Oklahoma City
2128 Northwest 25th Street, Oklahoma City, OK
Down$30kRateOn inquiry ~$450/mo$38,250
Owner Financing · $450 down
20 Acres Next to BLM Land Near Montello — $450 Down
Gamble District — APN 010-35H-046, Montello, NV
Down$450Rate0%Term7 yr ~$300/mo$21,900
Owner Financing · $300 down
10-Acre Lot in Montello, NV — Owner Financing
Gamble District — APN 010-37E-026, Montello, NV
Down$300Rate0%Term6 yr ~$400/mo$34,000
Owner Financing · $400 down
40.19 Acers 8 mins from a Reservoir
Rye Patch Road — APN 003-700-09, Lovelock, NV
Down$400Rate0%Term7 yr ~$1,421/mo$119,000
Owner Financing · $11.9k down · 4 bd · 2 ba · 1,188 sqft
4 Bed, 2 Bath Home in El Reno, OK — Owner Financing
145 North L Avenue, El Reno, OK
Down$11.9kRateOn inquiry ~$2,351/mo$215,000
Owner Financing · $10k down · 4 bd · 2 ba · 1,807 sqft
4 Bed, 2 Bath Home in Oklahoma City, OK — Owner Financing
1616 Southwest 62nd Street, Oklahoma City, OK
Down$10kRateOn inquiry
What is owner financing?
Owner financing means the person selling the property also finances it: instead of borrowing from a bank, you agree on a price, a down payment, an interest rate, and a monthly payment, and you pay the owner directly until the balance is paid off or refinanced. The deal is typically documented with a promissory note and a recorded security instrument such as a mortgage or deed of trust — the same kinds of paperwork a bank loan uses.
Buyers use owner financing when a traditional mortgage is out of reach or not worth the friction — self-employed income, a thin credit file, a property banks won't lend on (raw land especially), or a closing timeline measured in days instead of months. Sellers offer it because it widens the buyer pool, often supports a stronger price, and turns their equity into monthly income.
Every owner-financed listing on The Creative Marketplace shows the actual deal terms up front: asking price, down payment, monthly payment, and — where the seller shares it — the interest rate and term. You compare real numbers before you ever send a message, then deal directly with the seller on terms the two of you set.
One discipline we push on every deal: verify before you sign. Confirm clear title through a title company, understand any balloon payment and any loan that stays in the seller's name, and have a real estate attorney review the note. Owner financing is a widely used way to buy — the buyers who win with it are the ones who treat the paperwork as seriously as a bank would.
Owner Financing by state
Explore other financing
Owner Financing — frequently asked questions
- How does owner financing work when buying a home or land?
- You and the owner agree on price, down payment, interest rate, and monthly payment, then document it with a promissory note and a recorded mortgage or deed of trust. You pay the owner directly each month — the owner plays the role a bank normally would. In most structures the deed transfers to you at closing and the seller holds a lien.
- What credit score do I need for owner financing?
- There is no fixed minimum — each seller sets their own bar. Most weigh your down payment and income more heavily than your score, which is exactly why buyers with bruised or thin credit use owner financing. Expect a larger down payment to do the convincing a credit score normally does.
- How much down payment is typical on an owner-financed deal?
- Commonly 5%–20% of the purchase price, though it's fully negotiable — that flexibility is the point. Each listing on this page shows the seller's asking down payment so you can filter to what you can actually afford.
- Is owner financing the same as seller financing?
- Yes — the two terms describe the same structure: the owner of the property carries the loan instead of a bank. "Owner financing" is the more common consumer phrase; "seller financing" is the term you'll often see in contracts and notes.