Owner Financed Homes for Sale
Buy a house directly from the owner and pay them over time instead of qualifying for a new bank loan — with the down payment, monthly payment, and terms shown up front.
Latest owner financed homes
 ~$1,485/mo$150,000
Owner Financing · $7.5k down · 3 bd · 1 ba · 840 sqft
Owner Finance-5000 S Land Ave. Oklahoma City, OK 73119
5000 South Land Avenue, Oklahoma City, OK
Down$7.5kRateOn inquiry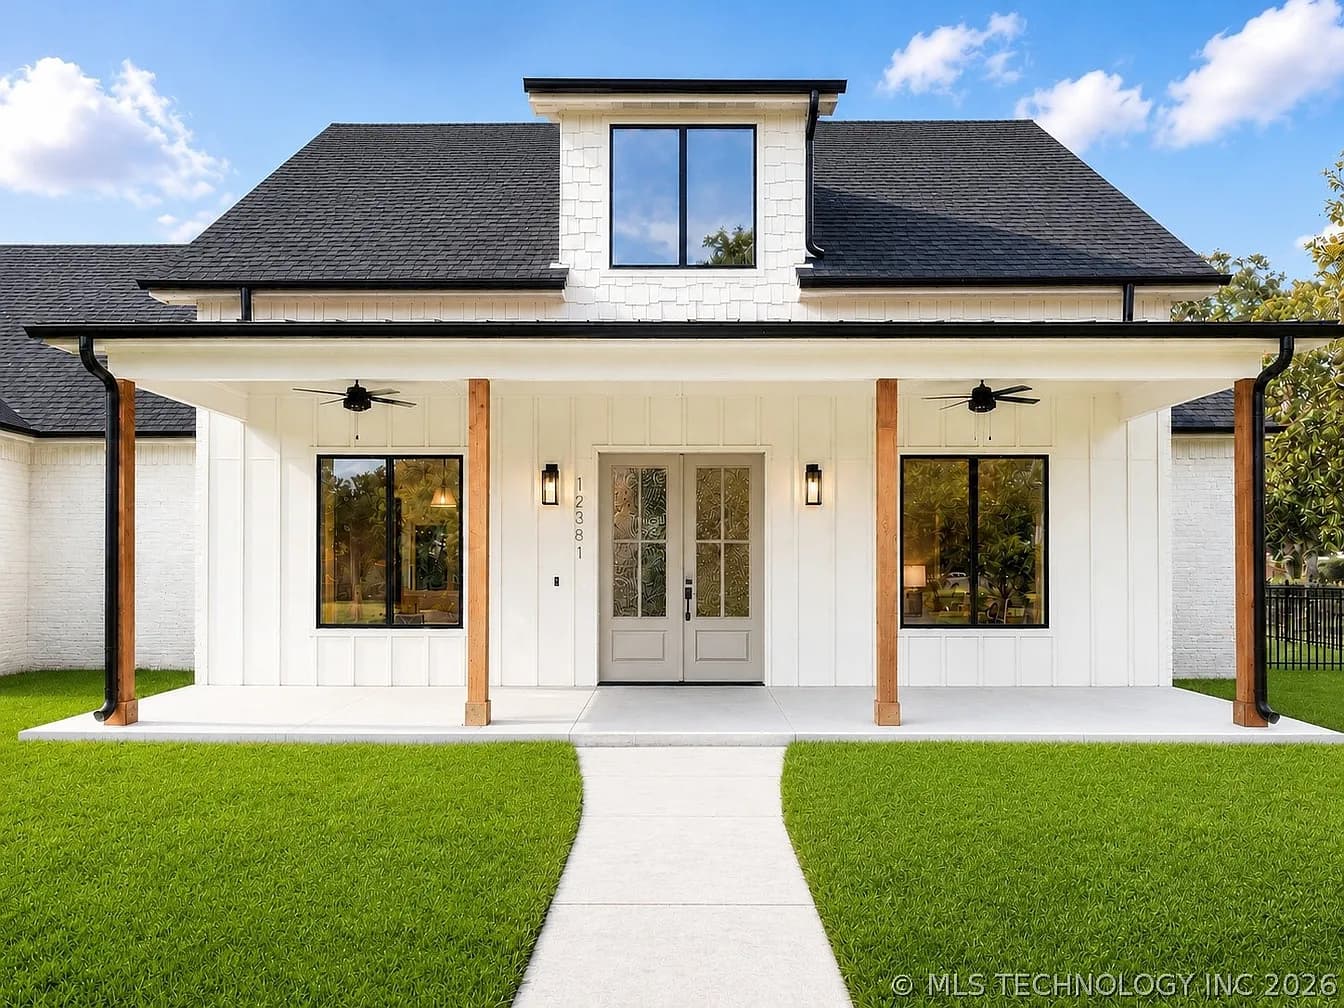 ~$8,096/mo$830,000
Owner Financing · $75k down · 4 bd · 4.5 ba · 3,785 sqft
Owner Finance-12381 Lakeview Rd Sperry, OK 74073
12381 Lakeview Road, Sperry, OK
Down$75kRateOn inquiry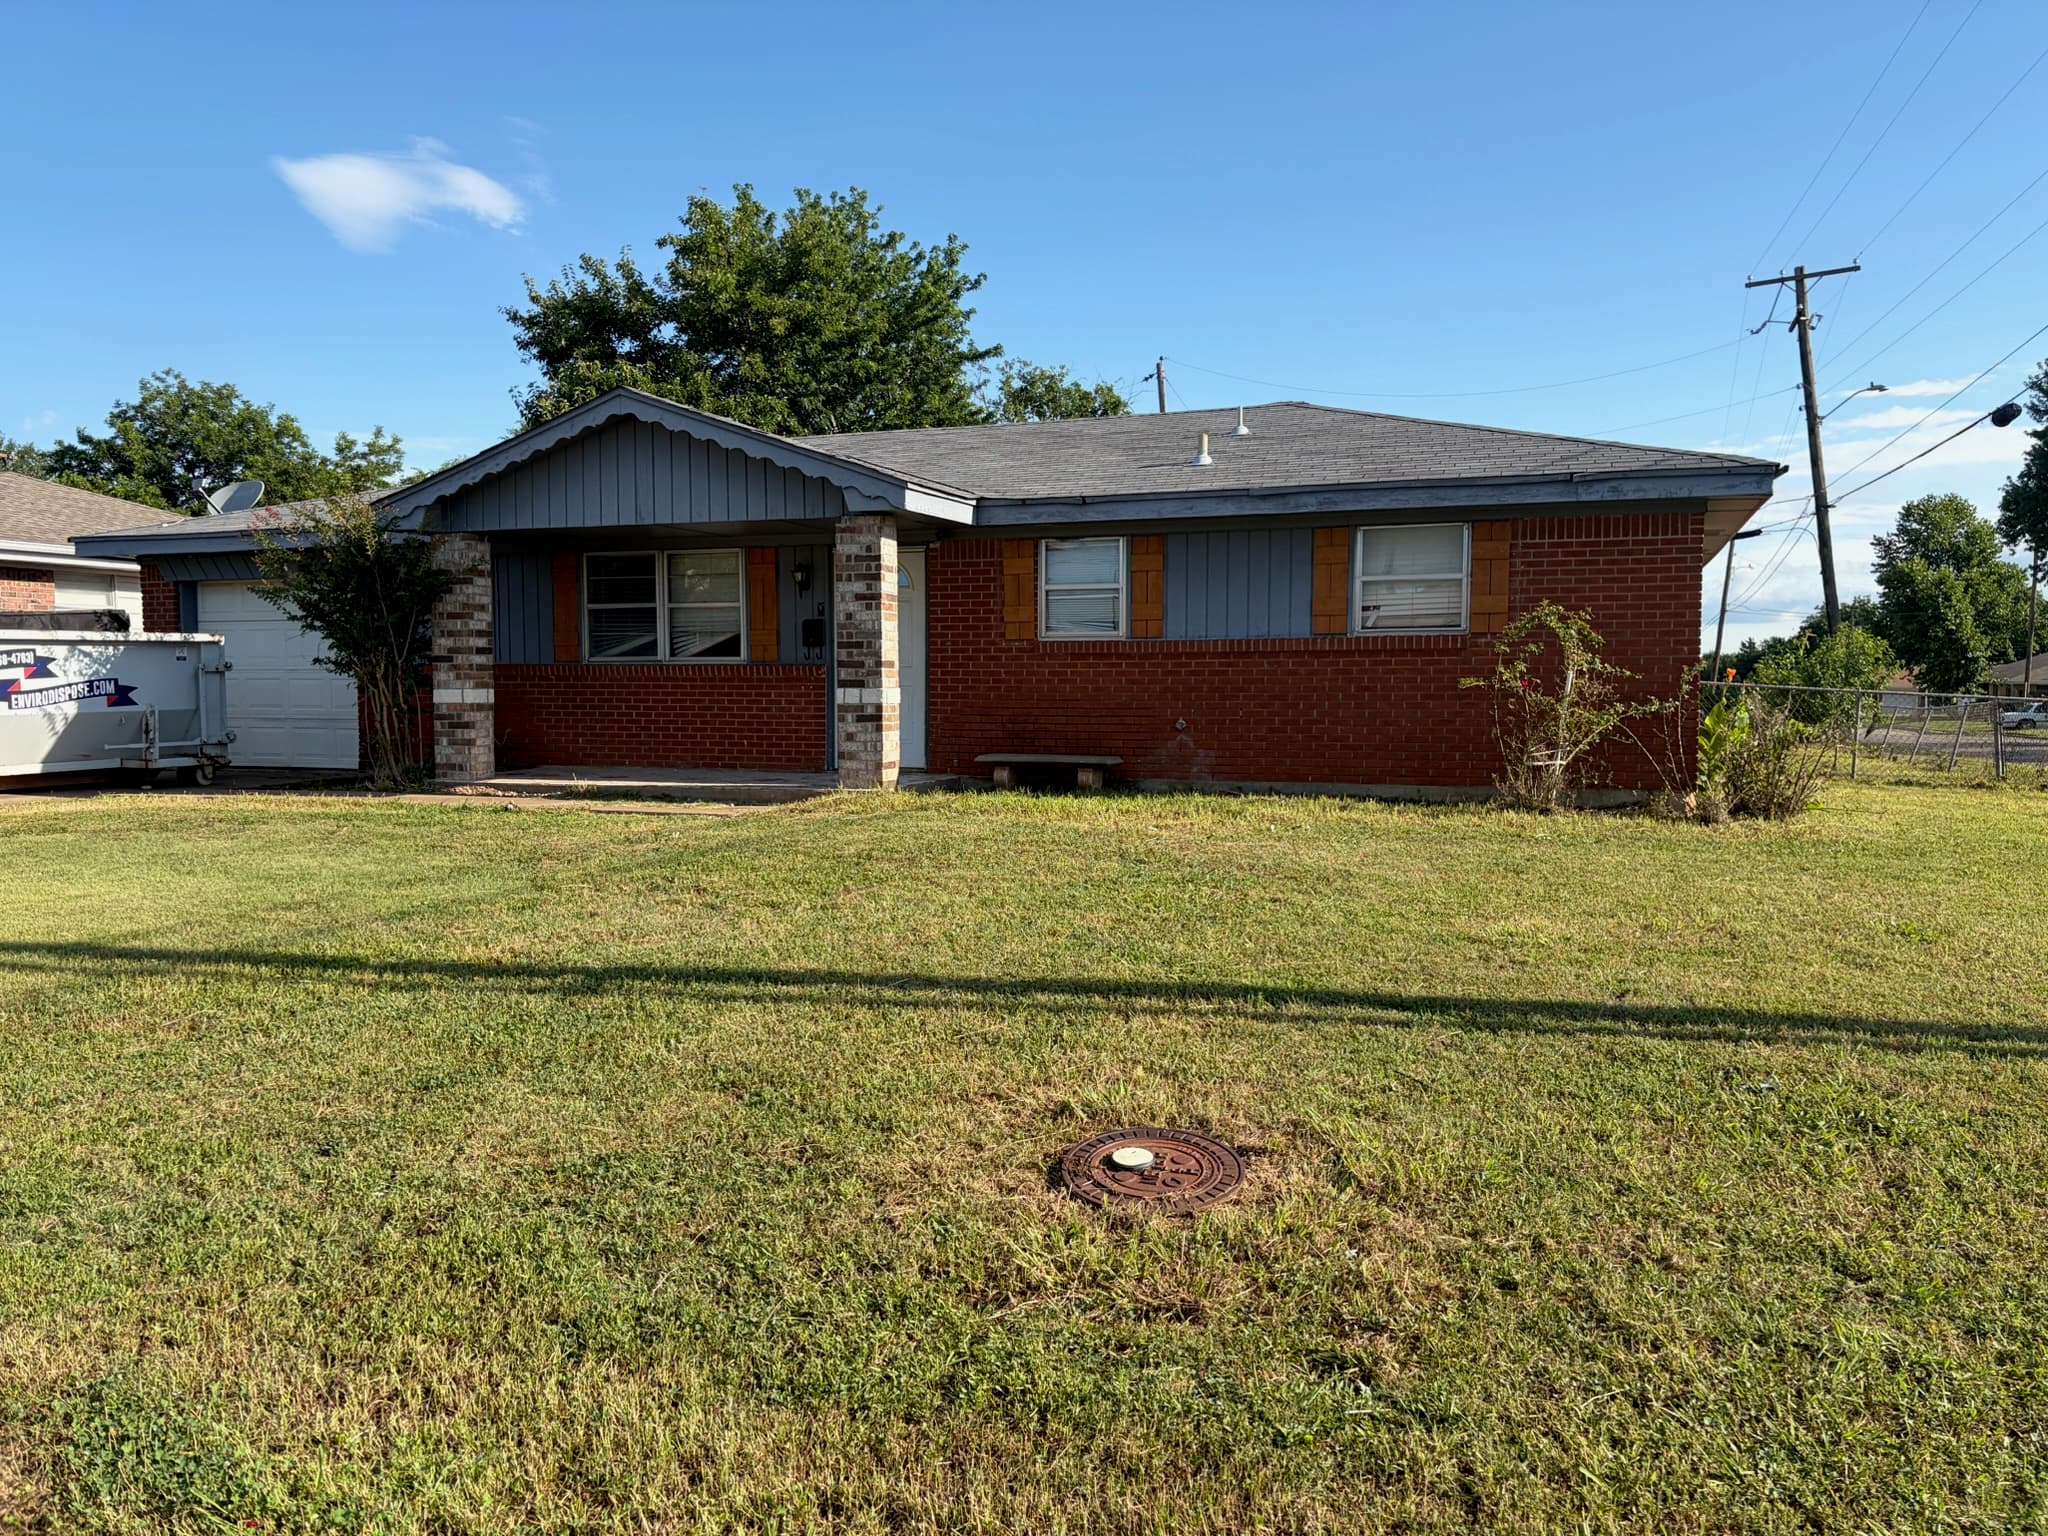 ~$1,496/mo$140,000
Owner Financing · $10k down · 3 bd · 1 ba · 1,115 sqft
Owner Finance-4773 SE 28th St. Del City, OK 73115
4773 Southeast 28th Street, Del City, OK
Down$10kRateOn inquiry ~$1,394/mo$130,000
Owner Financing · $10k down · 3 bd · 1 ba · 987 sqft
Owner Finance-3601 Parkwoods Ln Midwest City, OK 73110
3601 Parkwoods Lane, Midwest City, OK
Down$10kRateOn inquiry ~$1,825/mo$160,000
Owner Financing · $10k down · 3 bd · 2 ba · 1,389 sqft
Owner Finance-3113 Mockingbird Ln, Midwest City, OK 73110
3113 Mockingbird Lane, Midwest City, OK
Down$10kRateOn inquiry ~$1,870/mo$175,000
Owner Financing · $15k down · 3 bd · 1 ba · 1,130 sqft
Owner Finance-12 NE 66th St. Oklahoma City, OK 73105
12 Northeast 66th Street, Oklahoma City, OK
Down$15kRateOn inquiry ~$2,392/mo$225,000
Owner Financing · $10k down · 3 bd · 2 ba · 1,200 sqft
Owner Finance-1904 NW 7th, Oklahoma City, OKC 73106
1904 Northwest 7th Street, Oklahoma City, OK
Down$10kRateOn inquiry ~$6,501/mo$640,000
Owner Financing · $50k down · 5 bd · 3 ba · 3,488 sqft
Owner Finance-13120 Knight Island Drive Oklahoma City, OK
13120 Knight Island Drive, Oklahoma City, OK
Down$50kRateOn inquiry ~$1,500/mo$150,000
Owner Financing · $7.5k down · 2 bd · 1 ba · 832 sqft
Home in Midwest City, OK
515 East Ercoupe Drive, Midwest City, OK
Down$7.5kRateOn inquiry ~$1,700/mo$185,000
Owner Financing · $10k down · 3 bd · 1 ba · 953 sqft
Home in Oklahoma City, OK
6606 South Mckinley Avenue, Oklahoma City, OK
Down$10kRateOn inquiry
What is owner financing?
An owner financed home is a house you buy from the seller on payments: you agree on a price, a down payment, and a monthly payment, and you pay the seller directly instead of taking out a new mortgage. It's the same idea as owner financing on land, applied to a house you can move into.
Buyers look for owner financed homes when a traditional mortgage is slow, out of reach, or not worth the hassle — self-employed income, a short work history, a credit file that's still recovering, or wanting to close in days rather than months. Sellers offer it to reach more buyers and to turn their equity into monthly income.
Every home on this page shows the real numbers before you reach out: asking price, down payment, monthly payment, and — where the seller shares it — the rate and term. Compare homes side by side, then contact the seller directly.
Do the homework a lender would: get an inspection, confirm clear title through a title company, understand any balloon payment and whether a loan stays in the seller's name, and have a local real estate attorney review the paperwork before you sign.
Owner Financed Homes by state
Explore other financing
Owner Financed Homes — frequently asked questions
- How do owner financed homes work?
- You and the seller agree on the price, down payment, and monthly payment, and you pay the seller directly each month instead of a bank. The details — who holds title, when it transfers, and whether there's a balloon — are set in the paperwork, so read it closely and have a local real estate attorney review it.
- How much down payment do owner financed homes need?
- Each seller sets it. Down payments on homes commonly run 5% to 20% or more, and a larger down payment often earns better terms. Every home here shows the seller's asking down payment.
- Do I need good credit for an owner financed home?
- Each seller sets their own bar. Many weigh your down payment and income more heavily than your score, which is why buyers with a thin or bruised credit file look at owner financing.
- What should I check before buying an owner financed home?
- An inspection, a title search through a title company, the full payment schedule including any balloon, who pays taxes and insurance, and whether the seller still has a loan on the house. Have a local real estate attorney review the documents before you sign.